Business
Inflation, Interest Rates Fall

Indications emerged at the weekend that the current banking sector reforms and the relative stability in the prices of crude oil may have returned Nigeria to the path of economic stability with the remarkable reduction in inflation and interest rates.
The nation’s annual interest rates fell from 11 per cent in August to 10.4 per cent in September, thus raising the prospect of stability in the nation’s economy.
Data released by the National Bureau of Statistics at the weekend showed that the nation’s annual inflation dropped to 10.4 per cent on a 12-month basis in September from 11 per cent in August.
“The composite consumer price index or CPI rose 10.4 per cent year-on-year in September 2009 and it is slower than the 11 per cent increase recorded in the previous month,” the agency said in a report, giving no reason for the decrease.
“The monthly change of the CPI was 0.5 per cent increase in September 2009,” it added.
According to the bureau, the urban All Items Index rose by 0.2 per cent while the corresponding Rural Index increased by 0.7 per cent in September, when compared with the preceding month.
The bureau stated that the year-on-year average consumer price level as at September 2009 for urban and rural dwellers rose by 8.1 per cent and 11.5 per cent respectively.
Nigerian inflation had risen steadily since the second quarter of last year, standing at 9.7 per cent in May before soaring to 14 per cent in July owing to the effects of the global food crisis.
The Federal Government had managed to slow inflation for most of 2006 and 2007 through belt-tightening measures to achieve a single-digit rate.
Such measures included a stable exchange rate for the national currency, as well as fiscal discipline.
Checks also showed that the CBN intervention has also forced down interest rates which was pegged at 21 per cent earlier in the year. Interest rate now hovers between 18.85 and 19.89 per cent.
According to the latest figures posted on the Money Market Association site, Prime Lending rate stood at 18.85 while Normal lending was put at 19.85 per cent respectively.
In specific terms, the Nigerian Interbank Offer Rate (NIBOR) for call fell to 4.75 per cent by the end of last week from 10.37 per cent at which it closed the previous week ended October 9, 2009.
The 7-day NIBOR closed the week at 7.41 per cent from 12.50 per cent. The 90-day paper closed the week at 13 per cent from 16 per cent, while 180 day instrument dropped to 14.50 per cent as against 17.58 per cent the previous week.
Explaining the trading for last week, Head, Treasury Sales, Fidelity Bank Plc, Mr. Uvic Ogban said that the N200 billion bailout funds released to the second batch of troubled banks hit the system last week Thursday, thereby dragging down the rates.
“The market responded to the bailout fund. The other influence on the rates was the anticipation by dealers that the market will be awash with funds up till this week. The meeting of the Federation Account and Allocation Committee (FAAC) was held last week. It is expected that the fund will hit the system in the current week. In addition to the inflow expected from the economic stimulus package. Since the market respond to information, the foregoing will help sustain the low rates in the current week,” he said.
During an interactive session with journalists at the recently concluded World Bank/ International Monetary Fund (IMF) meetings in Istanbul, Turkey, CBN Governor, Lamido Sanusi, said the banking watchdog has been able to achieve macroeconomic stability, especially with both the exchange and interest rates.
He noted that when he became the CBN governor last June, inflation rate was 15 per cent but as at end of August, it had fallen to 11 per cent.
Sanusi said inflation was likely to go to nine per cent by the end of the year.
“When I became governor of Central Bank, inflation rate was 15 per cent. End of August, it was 11 per cent. The gap between the official rate and parallel rate was 25 per cent: as at today, it is 2.98 per cent. All short term money market rates today are lower than they were in December 2008.
“We’ve delivered macroeconomic stability. We’ve checked stable exchange rate-in fact, in the last one week; I have been fighting against the rapid appreciation of the naira because of return in confidence. It’s just that in the management of the macro economy, the CBN has been so successful and we’ve done all of these in the middle of all those financial turmoil.
“There’s been no spike on inter-bank rates. There’s been no spike on exchange rates. There’s been no capital flight and inflation has not gone up. Those are the facts the president mentioned in his Independence Day speech: Those achievements of his administration nobody talks about. Inflation is likely to go to nine per cent by the end of the year. Look at our exchange reserves, the foreign reserves- we stemmed the outflow: we were losing foreign reserves at the rate of $2 billion per month. In the last two months we have lost nothing,” he said.


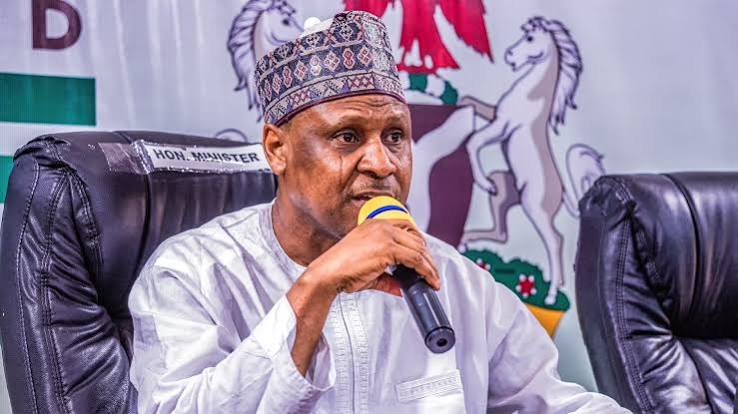
The Minister of State for Industry, Trade and Investment, John Enoh said this at the 8th annual induction and conference of the Chartered Institute of Project Managers of Nigeria (CIPMN).
He explained that abandoned projects continue to lock up public funds that could have been used for infrastructure development, industrial growth, job creation and essential social services.
Represented by the ministry’s Permanent Secretary, Chris Osa Isokpunwu, he said the impact goes beyond financial losses, as incomplete projects affect communities and limit access to important public services
He cited examples of that remain unopened, schools that cannot accommodate students, roads that fail to connect communities and electricity projects that have not delivered their intended benefits.
The Registrar-General and Chief Executive Officer of CIPMN, Henry Ifeanyi Mbadiwe, also identified poor project management as a major challenge affecting development in Nigeria.
He revealed that the institute had developed a project management curriculum for Nigerian universities, which has received approval from the National Universities Commission (NUC). The programme is expected to enable universities to offer project management as a bachelor’s degree.
Mbadiwe further referenced findings by the Presidential Projects Assessment Committee, which identified 11,886 ongoing federal capital projects in 2011, with an estimated financial commitment of ?7.78 trillion.
He noted that inadequate planning, supervision, accountability and implementation were among the factors contributing to the abandonment of projects across the country.
The minister called for stronger project management structures across ministries, departments and agencies to improve planning, monitoring and evaluation.
He added that the Federal Ministry of Industry, Trade and Investment had introduced a 90-day implementation reporting cycle to strengthen transparency and monitor the progress of government programmes.
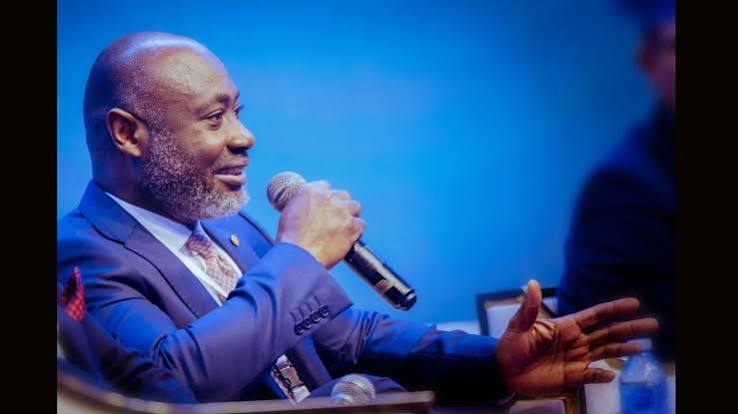
Ikenga said the company remained committed to Nigeria’s power sector and would continue investing in its operations despite the challenging business environment.
He spoke in Lagos at the third edition of the Shell Power Conference, themed “Powering Nigeria’s Progress: Turning Ambition and Action into Sustainable Impact”.
The Transcorp Power chief said the company would sustain electricity generation, invest in its facilities and deliver value to shareholders.
“Transcorp Power is a long-term player, not a short-term player. This year has been challenging, but what is important is getting power to schools, hospitals and businesses to power progress,” he said.
Ikenga said the company’s focus on operational efficiency and investment had strengthened its contribution to Nigeria’s electricity supply.
He disclosed that since acquiring the Ughelli Power Plant in Delta State in 2013, Transcorp Power had quadrupled its available generation capacity.
He also said the company became the first privatised power generation firm to receive a post-privatisation discharge certificate after fulfilling all its privatisation obligations.
The company’s unaudited results for the nine months ended September 30, 2026, showed a profit before tax of N83.1 billion, while its profit-before-tax margin rose to 31.2 per cent from 29.6 per cent recorded in the corresponding period of 2025.
Its total assets rose to 11.7 per cent amounting to N629.5 billion, while shareholders’ funds grew 8.9 per cent to N199.8 billion. Cash and cash equivalents also rose to N10.3 billion, supported by improved collections.
On the company’s contribution to grid stability, Ikenga said Transcorp Power’s black-start capability enabled it to restart operations without relying on electricity from the national grid.
He explained that the capability allowed the company to support power restoration following grid disturbances, helping to restore electricity supply to homes, businesses and industries.
Ikenga noted that Nigeria had an installed electricity generation capacity of about 13,000 megawatts, with an estimated potential of 50 gigawatts, adding that realising the potential would require effective coordination across the entire value chain.
“Everything in the value chain has to work,” he said.
He called for stronger collaboration among federal and state governments, regulators and private-sector operators, alongside increased private investment, to build a sustainable electricity market.
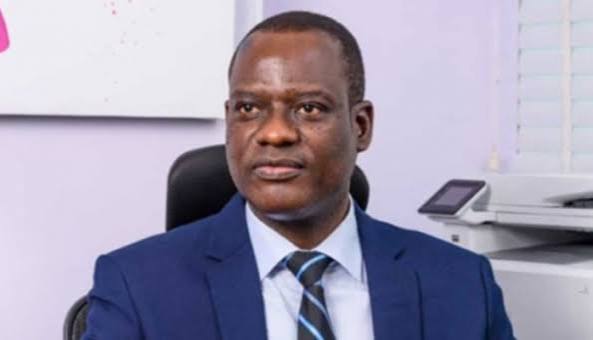
This was contained in a statement issued on Thursday by his Senior Special Assistant on Communications and Press Secretary, Maryann Duke.
The statement said Oyedele pointed to “improved digital systems, including electronic invoicing, as a key driver behind a record of N33tn in government revenue collected between January and October 2026.”
The minister said the performance demonstrated the potential of technology to improve revenue administration, strengthen compliance and increase efficiency across government institutions.
Speaking on the theme, ‘Digital Sovereignty and Ethics: Guarding the Economy for the Next Generation,’ Oyedele warned that Nigeria risked losing substantial economic opportunities if it continued to depend heavily on foreign digital infrastructure.
Citing Nigerian Communications Commission figures, he disclosed that the country recorded more than 157 million active internet subscriptions as of May 2026.
He explained that these connections generated significant volumes of information through financial transactions, healthcare, education and taxation.
However, citing estimates from the Nigeria Data Protection Commission, Oyedele said as much as 90 per cent of the country’s data was hosted abroad.
According to him, the situation has implications for foreign exchange expenditure, employment opportunities, technological skills and Nigeria’s control over information generated by its citizens.
He compared the country’s reliance on foreign digital infrastructure with its historical dependence on imported refined petroleum products, warning against a situation where Nigerian data would be processed abroad and the resulting services sold back to domestic users.
The minister consequently advocated greater investment in local data infrastructure, technical expertise, cybersecurity and predictable regulations to enable Nigerian businesses to capture more value from the digital economy.
He clarified that digital sovereignty should not translate into technological isolation but should strengthen Nigeria’s capacity to participate competitively in international markets.
Addressing graduating students, Oyedele urged young Nigerians to become developers of technological solutions rather than remain primarily consumers of products created elsewhere.
He identified artificial intelligence as both a disruptive force and an opportunity for innovation, advising graduates to acquire relevant digital skills alongside critical thinking, creativity, sound judgement and integrity.
The minister also cautioned against irresponsible online behaviour, explaining that digital footprints increasingly influence employment prospects, commercial relationships and professional credibility.
Oyedele outlined five priorities for graduates, including continuous learning, value creation, integrity, responsible digital citizenship and active participation in national development.
“Your degree is evidence of what you have learned. Your competence will demonstrate what you can do. Your character will reveal who you truly are,” he told the graduating students.
-
 Politics15 hours ago
LG CITY BOY COORDINATOR HAILS WIKE’S SUPPORT FOR ONYESOH, TINUBU
-
Politics15 hours ago
DIRI INAUGURATES APC CAMPAIGN COUNCIL, SETS MILLION VOTES TARGET FOR TINUBU
-
 Politics16 hours ago
NDC Candidate Urges Oborevwori To Probe Asaba Political Violence
-
Rivers4 days ago
NUJ Set To Attend UNIPORT’s 217th Inaugural Lecture
-
 News20 hours ago
Army Recovers X Account After Hack Attempt
-
 News4 days ago
NJC Suspends Three Judges, Sanctions Eight Others
-
Politics4 days ago
Atiku Kicks-Off 2027 Campaign, Promises To Tackle Nigeria’s Challenges
-
 Featured4 days ago
APC Presidential Campaign Storms PH, ‘Morrow