Oil & Energy
Another Look At The Nigerian Content Act

The Nigerian Content Development Act was signed into law in
2010 to achieve the domestication of significant portion of derivatives of the
oil and gas industry by ensuring the development and deliberate use of
indigenous human and material resources in the industry in Nigeria. It is
targeted at the adding value to the nation’s economy through the systematic
development capacity and capabilities by
using Nigerian human and material resources, and services in the industry.
The Act says Nigerian Independent Operators shall be given
first consideration in the award of oil blocks, oil licenses, oil lifting
licenses and all projects that have to do with oil blocks and oil licenses
particularly.
The intention of the Act therefore, is to build the Nigerian
Content by making it mandatory that some jobs in the industry are done in
country by Nigerians using Nigerian materials.
No doubt, the enactment of this Act ushered in a new era in
the oil and gas as prior to the Act, equipment used in the industry were
usually designed, fabricated and assembled abroad thus leading to capital
flight and export of jobs. There was a preponderance of expatriate workers
resulting to scarcity of jobs, paucity of skills and capacity building and utilization of
Nigerian workforce, culminating to economic under-development in the country.
Agreed, the law gave local entrepreneurs like Niger Dock,
Ladol, Daewoo, Saipem, LoneStar, Adamac among others the confidence to venture
into areas that hitherto were the exclusive preserve of multinational
companies.
According to the Executive Secretary of the Nigerian Content
Development and Monitoring Board (NCDMB), Engr. Ernest Nwapa represented by
Wole Akinyosoye the Act has to say the least opened a floodgate of acativities
in the industry which has resulted to a surge in indigenous capacity in the
industry.
Be that as it may, there still exist some gray areas that
need to be given some consideration. In terms of giving priority to indigenous
operators which the Act talked about, it is not explicit on the process which
the preferential treatment should be done.
For instance, on the list of 2012 to 2013 Crude Oil Contract
Holders, most of the companies have links with foreign owners while in some
cases an holder will be replicated but with different names.
There is also institutional problem as Nigerian National
Petroleum Corporation (NNPC) dominates contract allotment. So how and where
does the NCDMB come in, in terms of giving contracts.
Another gray area in the Act is the downstream Sector which
is the major concern of his piece. The downstream sector is not covered. Dr.
Eddie Wikina, while presenting a paper on “Promoting the Nigerian Content
through Deregulation of the Downstream Sector” at the just concluded Port
Harcourt International Oil and Gas Conference in Port Harcourt, noted that the
Act was restrictive as it does not cover the downstream sector of the
industry Dr. Wikina who is the managing
director of Treasure Energy Resource limited, a Rivers State Government oil and
gas firm, argued that in terms of Upstream business in the industry as touching
expatriate quota and using Nigerian materials, the Act has faired well but
nothing in the downstream.
The scope of the Act which is restricted to the upstream
sector, according to the oil and gas guru include services from within Nigeria,
goods manufactured in Nigeria, training and employment of Nigerians, location
of project office in catchment area or community, tax incentives for local
manufacturing, all fabrication and welding activities, insurance, legal and
financial activities.
He explained that
anybody who wants to build a downstream plant that is capable of employing up
to 5000 people in the country can do it with 100 per cent foreign labour,
foreign materials, foreign services and nobody will raise an eyebrow because
there is no law that says they must use Nigerian materials and services.
He pointed out that the downstream which has to do with
among others processing that convert oil nad gas into useful products including
distillation, cracking, reforming, blending,
storage, mixing and shipping has some regulatory control issues.
Some of the regulatory control issues, the TERL boss pointed
out were monopoly, closed market, price manipulation, lack of innovation,
investment block, value erosion, inefficient operations, foreign import
dependent, smuggling inter alia.
He therefore, recommended the review of the Act to
explicitly cover the downstream sector as this will open more opportunities for
participation of local indigenous operators and service providers thus leading
to growth of the Nigerian Content Development.
For instance, the coordinator of the 6th Nigerian Dredging
Summit, Exhibition and Award, Mr. Edmund Chilaka quoted NCDMB as saying that
$20billion oil and gas projects in the country were owned by foreigners and
noted that out of this whooping sum, only a paltry sum of less than $4 billion
was retained in Nigeria.
His words: “An estimate of over 150 times more jobs are
created in other countries than in Nigeria when Nigerian projects are being
executed.
“Ownership profile of marine assets supporting industry
activities has a current ratio of about 230 foreign owned vessels to a pitiable
20 Nigerian owned.”
Scenarios like the one painted above could be changed by
making the Act to cover the downstream as advocated by Dr. Wikina.
The TERL MD also recommended a full deregulation of the
downstream which would see government releasing the control on product prices.
He said it will open the market for more investors to come into the sector and
the emergence of more production facilities. Countries like Peru, Argentina,
Pakistan, Chile, Philippines, Thailand, Mexico, Canada, Venezuela, Japan,
United States of America (USA) among others have undergone complete
deregulation leading to a turn around of their economies. Government’s roles in
these countries have been drastically reduced thus giving greater freedom for
operators in the industry to operate and thrive which create room for healthy
competition and naturally drive down costs.
He enjoined government to completely end control on the
sector to allow independent operators to come in and money saved from subsidy
could be reinvested in local industries or used to support those ready to build
independent processing plants. And to a great extent add the much desired value
to the nation’s economy.
Federal Governments, he suggested should make funds
affordable by making investors in the industry have access to low interest rate
loans as this would serve as encouragement for them to venture into the
industry.
Commenting on the
difficulty of accessing funds by indigenous players in the industry, the
managing director of Harrybeath International Services Limited, Engr Agha Abani
said “You see the Nigerian government has good intentions to build capacity but
the problem most Nigerian companies have is in funding; we still have problems
of getting the required funding from the Banks. In the Western world, it is
much easier for them to finance this kind of projects but here in Nigeria it is
very difficult to get funding from the banks. So this is an area that has to be
looked at.”
Vivian-Peace Nwinaene


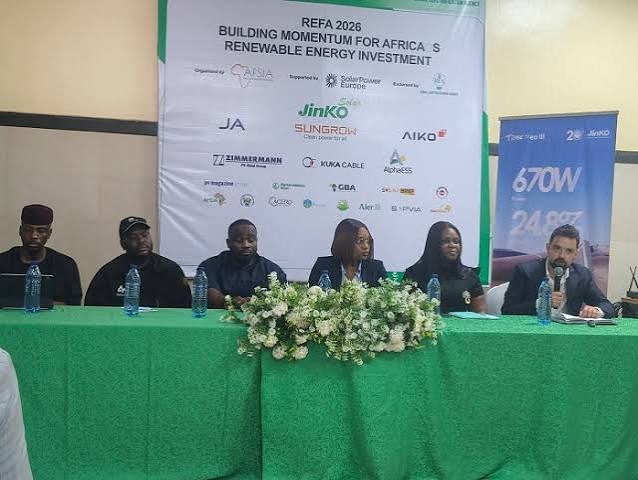
Nigeria’s growing solar market will take centre stage as the Renewable Energy Forum Africa (REFA) 2026 holds in Lagos on November 25-26 with the backing of the Rural Electrification Agency (REA).
Organised by the Africa Solar Industry Association (AFSIA) and supported by SolarPower Europe, the forum would bring together investors, developers, regulators, utilities and policymakers at the Radisson Blu Anchorage Hotel, Victoria Island.
The agency said the forum would strengthen partnerships, attract investment and support Nigeria’s clean energy and local manufacturing ambitions.
REA Managing Director, Abba Abubakar Aliyu, is billed to deliver the keynote address at the opening plenary.
The country also leads the continent in mini-grid capacity with 132MWp, while its commercial and industrial (C&I) solar capacity stands at 385MWp.
The market is receiving fresh support through the $750m World Bank-backed Distributed Access through Renewable Energy Scale-up (DARES) programme, targeting 1,350 mini-grids and electricity access for 17.5 million Nigerians.
-
Opinion4 days ago
Ancestorial Worship: My Take (1)
-
 Education16 hours ago
PAMO MEDICAL UNIVERSITY -Nullifies Arrest warrant on VC
-
Niger Delta17 hours ago
PANDEF Seeks 50% Oil Derivation Allocation Increase
-
Rivers15 hours ago
Don Seeks Repositioning Of Tech Education For Dev
-
 Education16 hours ago
IAUE MOVES TO END GHOST WORKERS SYNDROME AS 400 NEW NON-TEACHING STAFF UNDERGO MANDATORY ETHICS TRAINING
-
 News18 hours ago
Fresh Ebola Scare As NCDC Records Two Cases
-
News18 hours ago
Customs Partners EFCC, NDLEA, Others To Tackle Money Laundering, Terrorism Financing
-
 News4 days ago
FG Must Address Nigerians’ Concerns On Reforms -Shettima …Warns Against Misuse of AI, Social Media