Connect with us

Oil & Energy

Global Coal Consumption Hits Record Even As Coal Power Declines

Published

on

Global coal consumption reached another record in 2025, seemingly contradicting years of discussion about phasing out the world’s most carbon-intensive fossil fuel.
But the headline number does not tell the whole story.
The latest Statistical Review of World Energy shows that global coal consumption rose to 166.0 exajoules last year. That represented an increase of 0.7% from 2024.
At the same time, global electricity generation from coal declined. Coal-fired power production fell 0.3% to 10,511 terawatt-hours.
Those two trends are not mutually exclusive. Coal is used not only to generate electricity, but also in steelmaking, cement production, and other industrial processes. The divergence also reflects a changing geographic picture in which coal is declining across much of the developed world while remaining deeply embedded in Asia’s industrial economy.
A Record With Important Qualifications
Coal consumption reached a record in absolute terms, but it did not keep pace with overall energy demand.
Total global energy supply increased from 592.2 exajoules in 2024 to 600.3 exajoules in 2025, an increase of about 1.4%. Coal grew more slowly, so its share of the global energy mix slipped from 27.9% to 27.7%. Thus, despite the global record in coal consumption, coal lost a small amount of market share.
This pattern appears frequently during energy transitions. A fuel can continue growing in absolute terms even as faster-growing alternatives reduce its share of the total. With global energy demand still rising, losing market share does not necessarily mean declining consumption.
Renewable energy provides a relevant comparison. Renewable energy supply increased by nearly 10% in 2025, far outpacing coal. But the world’s appetite for energy was large enough to accommodate growth in renewables and another record for coal at the same time.
Coal Is Increasingly an Asian Fuel
The most striking feature of the coal market is its geographic concentration.
Asia Pacific consumed 138.1 exajoules of coal in 2025, accounting for 83.2% of the global total. China alone consumed 92.2 exajoules, or 55.6% of all the coal used in the world.
India contributed another 23.1 exajoules, representing 13.9% of global consumption. Together, China and India accounted for almost 70% of the world’s coal use. Add Indonesia, and the three countries consumed nearly 73% of the total.
This is why broad statements about a global coal phaseout can be misleading. Coal may be steadily retreating in Europe and North America, but its future is increasingly being determined in Asia.
Non-OECD countries accounted for 85.2% of global coal consumption in 2025. Their coal use has grown at an average annual rate of 1.9% over the past decade. OECD consumption, by contrast, has declined at an annual rate of 4.8%.
Europe consumed just 4.4% of the world’s coal last year. The European Union’s share was only 2.8%, following another 3.2% decline in consumption.
The global total therefore combines two very different stories. One is a long-term retreat from coal across much of the developed world. The other is coal’s continued importance to the large and growing economies of Asia.
One surprise in the 2025 data is that coal-fired electricity generation declined even as total coal consumption increased.
China generated 5,756 terawatt-hours of electricity from coal, down 1.1% from 2024. India’s coal generation fell 3.0% to 1,464 terawatt-hours. Since those two countries produce nearly 69% of the world’s coal-fired electricity, relatively small percentage declines can have a large effect on the global total.
Coal generation across Asia Pacific declined 1.2%, while Europe posted another 3.4% decrease. The European Union’s coal generation fell 3.6% and accounted for only 2.6% of the global total.
The divergence between consumption and power generation indicates that coal demand outside the electric power sector helped support the record. Coal consumption statistics include industrial uses that are not captured by electricity-generation totals. Changes in plant efficiency, coal quality, inventories, and measurement can also prevent the two series from moving in perfect alignment.
Whatever the precise combination, the result is notable. The world consumed a record amount of coal while producing less electricity from it.
The United States broke sharply with the broader developed-world trend in 2025.
U.S. coal consumption rose 10.4% to 8.7 exajoules. Coal-fired electricity generation jumped 13.1% to 804 terawatt-hours, while domestic coal production increased 4.4%.
In absolute terms, the increase in U.S. coal consumption was larger than the net increase for the entire world. U.S. consumption rose by about 0.8 exajoules, while the global total increased by roughly 0.7 exajoules. Declines in several other countries offset part of the American increase.
Still, this should not be mistaken for a return to coal’s former dominance in the United States.
U.S. coal consumption remains about 62% below its 2005 peak. Coal-fired generation is approximately 63% below its 2007 high, and production is about 54% below its 1998 peak.
The 2025 increase was substantial, but it occurred within a long-term structural decline. The United States still accounted for just 5.3% of global coal consumption and 7.7% of global coal-fired generation.
Global coal production remained near record levels at 180.8 exajoules, but it was essentially flat in 2025.
China increased production by 1.7% and supplied 52.4% of the world total. Its coal consumption was nearly unchanged, but its imports fell 10.1%. The combination suggests that increased domestic production displaced a meaningful amount of imported coal.
That shift helped push global coal trade down 3.1% to 35.3 exajoules. Indonesia, the world’s largest exporter, saw exports fall 7.4%. U.S. exports declined 11.5%, while Colombian exports plunged 21.3%.
Thus, record global consumption did not translate into record international trade. Much of the world’s coal is produced and consumed within the same countries, especially China and India.
The 2025 data support neither the claim that coal is disappearing nor the claim that the energy transition has stopped.
Coal use reached a record, but its share of global energy declined. Coal-fired electricity generation fell, but industrial and other uses kept total consumption elevated. Coal rebounded sharply in the United States but remained far below its historical peak. Europe continued to move away from coal, while Asia accounted for more than four-fifths of global demand.
The coal market is no longer one unified global story. It is a widening divide between countries that are steadily reducing their dependence on coal and countries where it remains central to electricity, industry, and economic development.
That divide is likely to continue defining the coal market for many years.
By Robert Rapier
Continue Reading

Oil & Energy

Renewable Energy Investment Forum Begins Nov. 25

Published

on

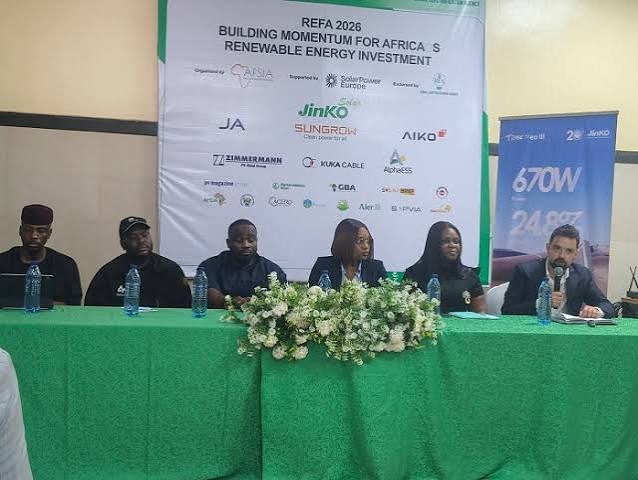
Nigeria’s growing solar market will take centre stage as the Renewable Energy Forum Africa (REFA) 2026 holds in Lagos on November 25-26 with the backing of the Rural Electrification Agency (REA).

Organised by the Africa Solar Industry Association (AFSIA) and supported by SolarPower Europe, the forum would bring together investors, developers, regulators, utilities and policymakers at the Radisson Blu Anchorage Hotel, Victoria Island.

The agency said the forum would strengthen partnerships, attract investment and support Nigeria’s clean energy and local manufacturing ambitions.

REA Managing Director, Abba Abubakar Aliyu, is billed to deliver the keynote address at the opening plenary.

The forum would also examine local manufacturing following the launch of Nigeria’s first privately owned 100MW solar module assembly plant in Ibeju-Lekki, Lagos.
The event would also feature B2B meetings, an exhibition and the AFSIA Awards on November 25.
It would be noted that Nigeria is West Africa’s leading solar market, with about 618MWp operational capacity, ranking first in the region and eighth in Africa, according to AFSIA.

The country also leads the continent in mini-grid capacity with 132MWp, while its commercial and industrial (C&I) solar capacity stands at 385MWp.

The market is receiving fresh support through the $750m World Bank-backed Distributed Access through Renewable Energy Scale-up (DARES) programme, targeting 1,350 mini-grids and electricity access for 17.5 million Nigerians.

Continue Reading

Oil & Energy

CBN Appoints Eight New Pre-shipment Agents For Crude Oil And Gas Exports

Published

on

The Central Bank of Nigeria (CBN) has appointed eight pre-shipment inspection agents to monitor crude oil and gas exports, alongside two monitoring and evaluation agents to oversee their activities.
The appointments, announced in a notice signed by Aderinola Shonekan, Director of the CBN’s Trade and Exchange Department, took effect on October 2, 2026, under the Nigerian Export Supervision Scheme.
The notice directs authorised dealer banks, the Nigeria Customs Service, petroleum regulators, terminal operators and oil and gas companies to comply with the revised arrangements.
The CBN assigned the eight inspection agents to specific crude oil and gas export terminals as part of the revised framework.
The allocations are as follows:
Dakee Engineering and Construction Ltd.: LNG, Escravos (Gas), Bonny River Terminal (BRT) and EGTL.
Trexem Energy Services Limited: Egina, Qua-Iboe and Tulja. Geoscape Limited: Escravos, ERHA, Odudu and FSO Cawthorne.
617 Limited: Bonga, Brass, Usan and Eagle.Robinson International Energy Ltd.: Ugo-Cha, Penington, Aje, Ima, Oyo and Nembe. Trobell International Nigeria Limited: Forcados, Bonny and Okwori.
Integrated Shipping Services Nigeria Ltd.: Akpo, Antan, Okoro, Anyala-Madu and Ebok.
Kephren Business Ltd.: Ukpokiti, Utapate, Yoho, Abo, Agbami, Ajapa, Okono, Okwok and additional marginal streams designated by the Nigerian Upstream Petroleum Regulatory Commission (NUPRC).
The CBN also appointed two monitoring and evaluation agents, the Q&Q Control Services Limited and the Arlington Securitas Nigeria Limited to oversee the inspection companies.
The Q&Q Control Services Ltd. would monitor 617 Limited, Trexem Energy Services Limited, Geoscape Limited and Kephren Business Ltd while the Arlington Securitas Nigeria Limited would monitor Dakee Engineering and Construction Ltd., Trobell International Nigeria Limited, Robinson International Energy Ltd. and Integrated Shipping Services Nigeria Ltd.
The latest appointments follow previous changes to the CBN’s monitoring arrangements for crude oil and gas exports.
The latest changes update the companies responsible for inspecting export cargoes and the terminals assigned to them. The notice requires the relevant institutions and operators to comply with the new allocations from October 2, 2026.
The appointments also come amid growth in Nigeria’s gas export earnings.
According to the CBN, Nigeria’s gas export earnings rose to $2.53 billion in the first quarter of 2026, reflecting stronger earnings from the country’s natural gas sector and contributing to its external trade position.
The revised inspection arrangements place designated agents in charge of specified export terminals, while the monitoring and evaluation companies oversee the inspection agents’ activities under the scheme.
Recall that in May 2024, the apex bank appointed 11 pre-shipment inspection and monitoring agents under the export supervision scheme.
The government subsequently reviewed the allocation of oil export terminals in March 2025, assigning additional terminals to nine inspection agents appointed under the scheme.
In July 2026, the CBN also appointed Candid Oil Services Limited as the pre-shipment inspection agent for the Taurus Oil and Gas Depot.
Continue Reading

Oil & Energy

What’s Next for Global Natural Gas Demand?

Published

on

The Iran war and the lack of LNG supply from the Middle East have upended forecasts of near-term natural gas demand and import costs.
So far this year, economies in Europe and Asia have relied more on renewables and coal for power generation to offset reduced gas supplies procured at very high prices.
This year’s crisis has prompted governments to rethink energy policies with energy security the top priority, again, after the 2022-2023 energy crisis.
After the decline in global gas demand this year, due to prices at four-year highs, the obvious question for gas market participants is where demand is going after the current crisis ends. Has the second gas crisis in four years permanently undermined expectations of long-term gas demand growth?
Gas cannot be replaced in many industrial processes, yet. Electricity-generating systems in major economies that have relied on gas for power cannot have a reliable electricity supply without gas.
Still, this year and over the past four years, key gas markets in Europe and Asia have seen the share of gas in their electricity mix decline.
The UK, the Netherlands, and Turkey, and major Asian economies China, Japan, and South Korea, have all seen the share of gas-fired electricity drop, according to data from think tank Ember cited by Reuters columnist Gavin Maguire.
The spike in natural gas prices has accelerated Europe’s renewables rollout, which took off in earnest earlier this decade when Russia invaded Ukraine in 2022 and cut off pipeline gas supply to most of Europe. The share of renewables has surged in the EU and the UK in recent years, gradually sidelining gas as the reliable backup fuel rather than the one meeting growing electricity demand.
Globally, “Gas is losing its share in the global power mix as renewables increasingly meet rising electricity demand,” Ember said in a report earlier this year. The analysis found that the share of gas in the global power mix declined for the fifth consecutive year in 2025, despite a small rise in absolute gas generation. Strong growth in clean power, led by solar and wind, met around 68% of global electricity demand growth over the five years to 2025, reducing the need for a significant rise in gas power generation
Related: Mexico’s Richest Man Sells $1.15 Billion in Oil Stocks
According to Ember, 61 out of 124 economies generating electricity from gas had passed their gas generation peak.
However, these countries accounted for around one-fifth of global gas-fired electricity generation in 2025. So the large gas-generating economies, albeit a smaller group, haven’t seen their peak in gas power generation.
The biggest emerging economies, China, India, and Brazil, have actually met their surging electricity demand without turning to gas, Ember noted.
China’s gas share remained close to 3% of the electricity mix in 2025 despite rapid demand growth, while gas power generation in India and Brazil plays a more limited balancing role, the think tank said.
“The economics and energy security case for electricity are increasingly moving in the same direction,” said Malgorzata Wiatros-Motyka, ?Senior Electricity Analyst at Ember.
“As renewables lower costs and reduce exposure to fuel price shocks and geopolitical disruptions, gas is steadily losing the advantages that once made it the default fuel for power system growth.”
The writing may have been on the wall for natural gas producers and exporters if natural gas was only used in power generation.
But natural gas key uses include as feedstock in industrial manufacturing, including cement and steel, as a chemical feedstock for fertilizer, or as the start of the supply chain of manufacturing plastics, paints, synthetic fabrics, and medicine, to name a few.
And then comes the biggest twist in energy and electricity demand forecasts in recent years—the AI boom. Data centers will drive a large part of the rise in global electricity demand, which has returned to growth even in the U.S. and Europe after a decade or so of flatlining. Renewable energy alone will not meet the surge in power demand, and gas will play a key role in America and in most of Asia, where many countries are positioning to become AI and data center hubs.
The biggest LNG producers, exporters, and traders see long-term gas demand growth intact despite this year’s supply shock that is reducing consumption amid spiking prices.
For example, Shell, the world’s biggest LNG trader, said in its annual LNG Outlook 2026 this summer that surging gas demand in South and Southeast Asia would push global LNG demand up by 65% by 2050 from 2025 levels, although growth this year has been stalled by the Strait of Hormuz crisis.
Shell sees global LNG demand increasing to nearly 700 million tons annually by 2050, up by around 65% from the 2025 levels of 422 million tons.
“The conflict created a system-wide shock with disruption cascading across all segments of the economy, but the LNG industry has proved resilient and able to adapt to changing market conditions,” Cederic Cremers, President of Integrated Gas at Shell, commented in the outlook.
“While more investment in both supply and demand infrastructure is needed, the long-term outlook remains strong and LNG will continue to be a stabilising force in the global energy system.”
The International Gas Union (IGU) said in its 2026 World LNG Report in July that “while LNG industry is not immune from the challenges of operating in an era of heightened geopolitical uncertainty, its unique ability to re-distribute large quantities of clean-burning energy from a broadening supply base only enhance LNG’s role as a ‘shock absorber’ to the global economy.”
By; Tsvetana Paraskova
Continue Reading

Trending