Oil & Energy
The Nuclear Industry’s Trillion-Dollar Question

In the inbox of Petr Zavodsky, director of nuclear power plant construction at Czech power group, CEZ are three sets of proposals from American, French and Russian consortiums, all angling for a $30 billion contract to build five new reactors.
State-owned CEZ, central Europe’s biggest utility group, plans to build two additional units at its Temelin plant near the Austrian border as well as up to two other units in neighbouring Slovakia and another at its Dukovany station in the east of the Czech Republic.
In the running to build the plants are Toshiba Corp unit Westinghouse, an alliance of Russia’s Atomstroyexport and Czech firm, Skoda JS, and France’s Areva.
Unlike Germany, which has said it will hasten its exit from nuclear energy following the crisis in Japan, and Italy, which has announced a one-year moratorium on plans to re-launch atomic power, the Czech Republic has no intention of slowing its push for more nuclear power.
Less than a week after the Fukushima disaster, Prime Minister Petr Necas said that he could not imagine that Prague would ever close its plants. “It would lead to economic problems on the border of an economic catastrophe.”
At the same time there’s little doubt the Fukushima crisis will change the Czech Republic’s thinking about safety in the new plants — and that could influence whose bid will ultimately be successful.
“Nuclear energy works on the basis of lessons learned from past events,” Zavodsky told Reuters. “We will analyze what happened in Japan and will surely include recommendations arising from this analysis for suppliers in the tender.”
That is just one way the Japan crisis is already changing the game for the nuclear industry.
Before Fukushima, more than 300 nuclear reactors were planned or proposed worldwide, the vast majority of them in fast-growing developing economies. While parts of the developed world might now freeze or even reduce their reliance on nuclear, emerging markets such as China, India, the Middle East and Eastern Europe will continue their nuclear drive.
But with fewer plants to bid on, the competition for new projects is likely to grow even fiercer — and more complicated. Will concern about safety benefit Western reactor builders, or will cheaper suppliers in Russia and South Korea hold their own? And what if the crisis at Fukushima drags on as appears likely? Could it still trigger the start of another ice age for nuclear power, like Chernobyl did in 1986? Or will it be a bump, a temporary dip in an upward growth curve?
With nuclear plants costing several billion dollars apiece, the answer to those questions may be worth a trillion dollars to the nuclear industry. Little wonder that the main players have rushed to reassure their clients that all is well.
On March 15, just three days after the first Fukushima reactor building blew up, Russian Prime Minister Vladimir Putin flew to Belarus to revive a $9 billion plan to build a nuclear plant there, saying that Russia had a “whole arsenal” of advanced technology to ensure “accident-free” operation.
The next day, President Dmitry Medvedev met with Turkish Prime Minister, Tayyip Erdogan in Moscow, and pledged to press ahead with a $20-billion deal to build a four-reactor Russian plant in Turkey. “The answer is clear: it can be and is safe,” Medvedev said.
It was a similar message in France, the world’s most nuclear-dependent country with 58 nuclear reactors that provide almost four-fifths of its electric power. “France has chosen nuclear energy, which is an essential element of its energy independence and the fight against greenhouse gasses,” President Nicolas Sarkozy said after his government’s first post-Fukushima cabinet meeting. “Today, I remain convinced that this was the right choice.”
The American nuclear industry has also gone on a public relations drive. The industry’s main lobby group, the Nuclear Energy Institute, has been out in force in Washington since the disaster, kicking off its response with a meeting three days after the quake in which it briefed 100 to 150 key aides to US lawmakers on the crisis.
“Our objective is simply to be sure policymakers understand the facts as we understand them,” Alex Flint, vice president for governmental affairs at the institute told reporters. To appreciate how much is at stake for the industry it’s worth remembering that until Fukushima the prospects for nuclear power had been at their brightest in more than two decades, reversing a long period of stagnation sparked by the Chernobyl disaster.
The number of new reactors under construction, up to 30 or more per year in the 1970s, dropped to low single digits in the 1990s and early 2000s; by 2008 the total number of reactors in operation was 438, the same number as in 1996, International Atomic Energy Agency data show. In the past few years, that trend has reversed itself, and in 2008 construction started on 10 new reactors, the first double-digit number since 1985.
Today, there are 62 reactors under construction, mainly in the BRIC countries (Brazil, Russia, India and China), with 158 more on order or planned and another 324 proposed, according to World Nuclear Association data from just before Fukushima. China, which currently has just 13 reactors in operation, has 27 more under construction and was planning or proposing another 160. India was planning or proposing 58 and Russia 44.
Anti-nuclear lobby activists argue that demand for safer designs will make nuclear power more expensive. That should help low-carbon renewables such as solar and wind, and end nuclear power’s momentum according to Greenpeace EU Policy Campaigner Jan Haverkamp. “Fukushima will end all this talk about a nuclear renaissance. The industry says nothing will change. Forget it,” Haverkamp said.
But even if Fukushima does increase public resistance to nuclear, it seems unlikely to stop the emerging market countries’ nuclear ambitions altogether. For one thing, public opinion in Asia does not drive policy like it does in the West. Even India, with a democratic tradition and a post-Bhopal sensitivity to industrial disasters, seems set to keep its nuclear plans on track.
“The global socio-political and economic conditions that appear to be driving the renaissance of civil nuclear power are still there: the price of oil, demands for energy security, energy poverty and the search for low-carbon fuels to mitigate the effects of global warming,” Richard Clegg, Global Nuclear Director at Lloyd’s Register said.
Few companies have more at stake than France’s Areva, the world’s largest builder of nuclear reactors. Even before the Japan crisis, the state-owned firm touted its next-generation, 1,650 megawatt reactor — designed to withstand earthquakes, tsunamis or the impact of an airliner — as the safest way to go.
Now Areva’s ramping up that message whenever it can. “Low-cost nuclear reactors are not the future,” Areva CEO Anne Lauvergeon told French television just days after the first explosion at the Fukushima plant.
But Areva’s new EPR reactor is not without its own issues. Originally called the “European Pressurized Water Reactor” (EPR), Areva’s marketers later re-baptized it the “Evolutionary Power Reactor”. Anti-nuclear activists mockingly refer to it as the “European Problem Reactor” because of its troubled building history.
Designed with multiple and redundant back-up systems to safeguard against natural disasters, the EPR’s design was updated after 9/11 to be able to withstand the impact of an airliner crashing into it. Areva’s Chief Technical Officer Alex Marincic says that the EPR’s design reduces the probability of a core meltdown to less than one in a million per reactor per year, compared to one in 10,000 for older second-generation reactors.
Even if the worst were to occur, the EPR comes with a “core catcher” below the reactor containment vessel that is designed to prevent a melting reactor from burrowing China Syndrome-style into the ground.
Marincic said that the EPR, and in particular its back-up diesel generators, would have resisted the force of the tsunami wave in Fukushima as all buildings and doors are designed to be leak tight and to withstand the force of an external explosion.
“Had the reactor in Fukushima been an EPR, it would have survived,” he said.
Construction of the first EPR started in 2005 in Olkiluoto, Finland, where Areva signed a three billion euro turnkey contract with Finnish utility TVO. But due to a string of construction problems, the project is now three years behind schedule and nearly 100 percent over budget. The reactor is not expected to come on stream before 2013 and Areva is embroiled in a bitter arbitration procedure with the Finns over who will shoulder the extra costs.
Work on a second EPR started in Flamanville, France in December 2007 and is expected to be completed in 2014, also after several years’ delay. French utility group EDF says that in 2010 the investment cost for the reactor was estimated at about five billion euros.
Areva is also building two EPRs in Taishan, southern China, due to come on stream in 2013 and 2014. Areva says that contract was worth eight billion euros.
The size of nuclear deals varies widely depending on what is included. At a minimum, a vendor can sell a reactor or a license to build it. But vendors can also take on construction of the reactor building or even the entire nuclear plant. Deals often also include long-term contracts for nuclear fuel delivery or financing by firms in the vendor country. Building costs also range enormously depending on where the plants are built.
In resource-poor India, for instance, where Areva is negotiating the sale of two EPRs, the deal could include 25 years of fuel deliveries, an Areva spokesman, said. CEO Lauvergeon has referred to Areva’s strategy as the “Nespresso model” — Areva not only sells reactors, it enriches and sells uranium, and can recycle the spent fuel.
A French official said on condition of anonymity that Chinese authorities have told French partners that following the Fukushima disaster China now wants to use third-generation reactor designs for its smaller power plants.
This would be a huge boost for Areva, which is developing — with Japan’s Mitsubishi Heavy Industries — a new 1,100 megawatt ATMEA1 pressurized water reactor designed to supply markets with lower electricity needs.
Areva spokesman, Jacques-Emmanuel Saulnier, said the group is currently negotiating some twenty projects in countries including the United Kingdom, the United States, India, China and the Czech Republic. The firm still hopes to capture one third of the market for new reactors by 2030, though the Fukushima events may push back that target date.
Areva’s main competitor is Toshiba Corp unit Westinghouse, which is building four of its third-generation “Active Passive” AP1000 reactors in China, with the first expected to go on-line in 2013.
To be Cont’d
Culled from Reuters.


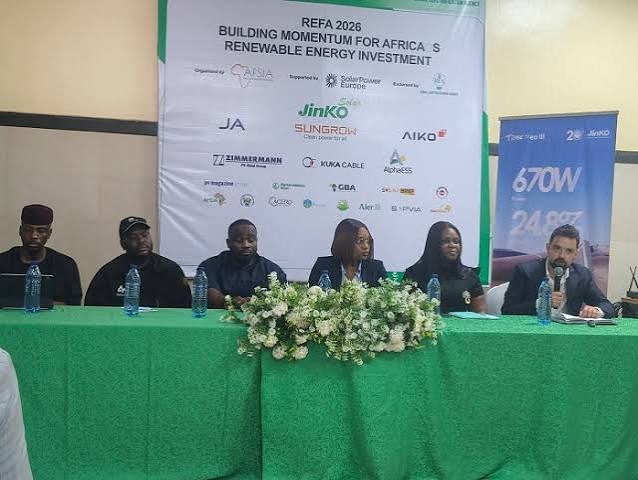
Nigeria’s growing solar market will take centre stage as the Renewable Energy Forum Africa (REFA) 2026 holds in Lagos on November 25-26 with the backing of the Rural Electrification Agency (REA).
Organised by the Africa Solar Industry Association (AFSIA) and supported by SolarPower Europe, the forum would bring together investors, developers, regulators, utilities and policymakers at the Radisson Blu Anchorage Hotel, Victoria Island.
The agency said the forum would strengthen partnerships, attract investment and support Nigeria’s clean energy and local manufacturing ambitions.
REA Managing Director, Abba Abubakar Aliyu, is billed to deliver the keynote address at the opening plenary.
The country also leads the continent in mini-grid capacity with 132MWp, while its commercial and industrial (C&I) solar capacity stands at 385MWp.
The market is receiving fresh support through the $750m World Bank-backed Distributed Access through Renewable Energy Scale-up (DARES) programme, targeting 1,350 mini-grids and electricity access for 17.5 million Nigerians.
-
Rivers2 days ago
Don Seeks Repositioning Of Tech Education For Dev
-
 Education2 days ago
PAMO MEDICAL UNIVERSITY -Nullifies Arrest warrant on VC
-
Niger Delta2 days ago
PANDEF Seeks 50% Oil Derivation Allocation Increase
-
 Education2 days ago
IAUE MOVES TO END GHOST WORKERS SYNDROME AS 400 NEW NON-TEACHING STAFF UNDERGO MANDATORY ETHICS TRAINING
-
 News2 days ago
Fresh Ebola Scare As NCDC Records Two Cases
-
News2 days ago
Customs Partners EFCC, NDLEA, Others To Tackle Money Laundering, Terrorism Financing
-
 Politics2 days ago
2027: South-East Govs Insist On Tinubu’s Re-election
-
 Politics2 days ago
2027: RIVERS GUBER CANDIDATES SIGN CHARTER TO PRIORITIZE CITIZENS’ DEMANDS