Business
Capacity Building/Local Content in Oil, Gas Insurance

Nigeria is a richly blessed nation both in terms of huge population and its natural resource endowments. With a population estimated at about 140 million, Nigeria is the largest country in Africa and it is home to one-sixth of the black population in the world. Nigeria is the 8th largest oil producer and has the 6th largest deposit of natural gas in the world. Only about 40 per cent of its arable land is currently. under cultivation. From the North to the South, its greatness is evident. The premium it places on higher education is underscored by the existence of over 100 tertiary institutions which collectively produce more than 200,000 graduates per annum. There are abundant solid mineral deposits in all parts of the country that remain largely untapped. In spite of these intimidating statistics, development has not taken place in profound proportions in Nigeria since independence in 1960. The poverty level is very high as over 70 per cent of population remains poor. With its endowments, this is clearly an irony.
Oil Sector and rest of the economy
Economic experts have agreed that development has taken place when the standard of living of the citizenry increases with economic growth measured in terms of statistical rise in gross domestic product (GDP). Over the years, the Nigerian nation has experienced phenomenal growth in its GDP caused by huge oil exports and rise in price of crude oil in the global market. For instance, the nation’s GDP increased from N4,7999,66m in 1999 to NI8,222,800m in 2006. On the average, Nigeria spends US$lObillion in the oil and gas sector annually. The impact of this growth and huge investment on the populace has not been as fundamental in terms of employment generation, improved standard of living, linkage with other sectors, upgrade of infrastructure, etc, as 80 per cent of the sector are in the hands of foreigners. For instance, the per capita income for the same period merely increased from US$463.23 to US$1 ,011.73 implying that on the average, each of us lives on US$3 per day! The situation is made worse, according the recent report of Nigerian Extractive Industries Transparency Initiative (NEITl), by lack of transparency in the sector. Only about 5 per cent of the oil and gas sector’s insurance business is in the hands of the local underwriters while about 3 per cent of the nation’s entire work force is engaged in the sector which generates over 75 per cent of the foreign exchange earnings.
Local Content Policy
It is to address this unacceptable scenario that the government evolved the local content policy for the oil and gas sector with the following targets: 45 per cent local content by 2006 and 70 per cent local content by 2010. To drive the process, the Nigerian National Petroleum Corporation (NNPC) created a Content Division which resulted in the setting up of the Nigerian Content Support Fund (NCSF) with take off grant of US$35Om. The Local Content initiative was to facilitate the transfer of technology, human capital development, greater employment of Nigerians, enhance linkage with other sectors, etc. Since the existence of this fund is not even known to many stakeholders, it is not a surprise that several years after the policy was initiated, the oil and gas industry is still chiefly in the hands of foreigners. The level of local personnel trained and technical skills imparted are abysmally low as emphasis is only on welding and fabrication while the top echelon is reserved or dominated by foreigners. Ancillary services like insurance are not even given serious consideration. This has severe implications for the nation and its people because oil is a wasting asset. Except the output and resultant revenue from the sector impacts the nation and its people positively, investments in the sector would have produced sub-optimal results. A clear case of living near the river and remaining perpetually thirsty. Secondly, the environment would have been destroyed without anything done to restore it such that it can continue to sustain life. Thirdly, the resources from the nation would just be devoted to financing the economies of other countries. As more and more foreigners are engaged to work in the sector, the huge incomes they earn will be passed to their home country for developmental activities. The view is rife that except the massive investment, exploration and progress recorded by the oil and gas sector have domino effects on other sectors, the nation will not optimally benefit from this natural endowment. Here lies the propriety of the theme for this year’s Insurance Stakeholders’ Parliament, “Developing Local Content and Capacity Building in the Oil and Gas Insurance Business”.
Capacity Building
Insurance is about risks and the management of uncertainties. The determination of the quantum of risks, probability of occurrence and the provision of cover are within the purview of an insurance expert. To say the least, the risks in the oil and gas industry are enormous and involve huge financial outlays and therefore, require sound technical capacity to accurately assess them. Indeed, oil giants strongly believe that insurance underwriters are both under-capitalised and have inadequate technical expertise to handle insurance risks in the sector. Against the foregoing, underwriters need to build capacity if they are desirous of venturing into this high-risk sector.
Capacity building in the oil and gas sector can be viewed from two perspectives: financial capacity to execute projects and the technical expertise to appreciate the thrust and severity of the business to be undertaken as well as the ability to execute same. Technical capacity in the insurance business in general has been a serious problem and, indeed, one of the driving forces behind the recently concluded consolidation. The view was rife that consolidation will improve the synergies of underwriters as they would have, not only a large pool of personnel to draw from, but also, they can invest some of their funds in training. While it is too early to assess the extent to which consolidation has produced the desired results, I noted in an earlier write-up that, the raising of funds to meet the minimum level of capitalisation set by the National Insurance Commission may be easy, but the development of human capital will not be easy. It will take time. Capacity building involves long gestation.
As you are aware, the occurrence of disasters of profound proportion and devastating impact has become commonplace in our time. This development should ordinarily not pose any problem to insurance companies and practitioners since this is their stock in trade. What has become challenging to insurance practitioners today is, among others, the dearth of requisite technical capability and expertise to effectively manage the special risks associated with certain classes of insurance business as well as handle emerging crises. Yet, due to the absence of a solid capital base, managers of insurance companies erroneously perceive investment in the needed human capital both as wastes and as avoidable costs. No wonder, in carrying out re-engineering programmes, the first casualties are usually staff layoffs and drastic reduction in the budget of training! It is therefore not a surprise that the affected companies were unable to easily deliver on their contractual obligations. To achieve the desired level of human capital development will take much longer time and resource. In terms of financial capacity, the challenge is not as fundamental as underwriters can form consortia to handle businesses irrespective of size and even encourage reinsurance to take on some of the risks beyond a certain threshold. The existence of even a fund created by the Nigerian National Petroleum Corporation which is supported by financial institutions point to the fact that the issue of financial muscle can be addressed without much difficulty.
Compliance to Local Content Policy
In spite of the perceived un-sophistication of the insurance business in Nigeria by the oil majors, it must be encouraged to develop to reach the best international standards. This can only happen through consistent patronage. The oil majors must be compelled to patronise local underwriters in the long-term interest of the nation in addition to the foreign exchange to be saved. Except this happens, the incentive to invest in capacity building by local underwriters will diminish. In this respect, the contracts with oil companies have to be reviewed to ensure greater value for Nigeria. Mandatory compliance clauses on local content need to be part of the agreements. The companies cannot be expected to voluntarily comply with the local content policy of the government, as it does not promote their interest and that of their home countries. This position was succinctly advocated by a 2006 Nobel Laureate in Economics, Prof. Stiglitz (2006: 150) when he argued that “the major responsibility for getting as much value as possible from their natural resources and using it well resides with the countries themselves. The first priority should be to set up institutions that will reduce the scope for corruption and ensure that the money derived from oil and other natural resources is invested, and invested well. It may be desirable to have some hard and fast rules for that investment- a certain fraction devoted to expenditures on health, a certain fraction to education, and a certain fraction to infrastructure. Procedures need to be put into place for independent evaluations of the returns on investments. Stabilization funds are essential. “Except this is done, ultimate benefits will be sub-optimal. This is a choice that we need to make. Stiglitz went further to argue that, “natural resource curse is not fate; it is choice”. We must make the right choice now.
Manpower development in the insurance industry
Although, the history of insurance industry dates back to the 1921 when the Royal Assurance Agency was established in Lagos, it was not until February 1993, when the Act establishing the Chartered Insurance Institute of Nigeria (CIIN) was enacted. This implies that for over 70 years, insurance was not considered a profession, in spite of its immense contributions to the growth of business and the national economy.
In spite of the fact that a lot of Universities and Polytechnics now run degree and diploma courses in insurance, this is just a prelude to the production of qualified insurance practitioners and therefore . grossly inadequate. Given the Federal Government’s policy of not financing professional institutes, it would be foolhardy to expect CIIN to be able to produce the large number of professionals required by the sector. Even the annual sponsorship of a few Nigerians to the West African Insurance Institute in Liberia for shortterm courses by the erstwhile govemment-owned Nigerian Reinsurance Corporation in an effort to bridge the skills gap, has remained a drop in the ocean. In view of this, the Petroleum Training and Development Fund (PTDF) must begin to give attention to the training of personnel in insurance, accounting, economics and finance as these are germane to the virility of the oil and gas business. The insurance companies should join forces to assist the CIIN to fast track the production of specialist for the industry.
Conclusion
The local content policy of the government is a well-thought out initiative designed to accelerate the involvement of Nigerians in the all-important oil and gas sector. Several years after it was evolved, not much has been achieved. Although there are no statistics to validate the extent of compliance to the targets of 45 per cent in 2006 and drive towards 70 per cent of 2010, the continuous dominance by foreigners of the commanding heights of the sector bear eloquent testimony to the need for urgent actions by the government and regulatory bodies.
The questions for the insurance Industry are :
How can existing underwriters develop the technical capacity to assess the risks inherent in the sector?
How can they develop the fmancial capacity to underwrite such high-risk insurance business given their poor level of capitalisation?
What is the state of reinsurance business in Nigeria?
How can market-induced consolidation in the insurance sector help?
What role can NAICOM play in this respect?
Local underwriters are currently engaged in different classes of insurance business. What role will specialisation play in helping them to secure oil and gas insurance business?
The 2009 Insurance Stakeholders’ Parliament will provide an opportunity for the articulation of action plans that would address this unacceptable development. You must participate to appreciate the significance of the forum.
Mrs. Babington-Ashaye is the MD/CEO, Risk Analyst Insurance Brokers Limited, Lagos.

Funmi Babington-Ashaye


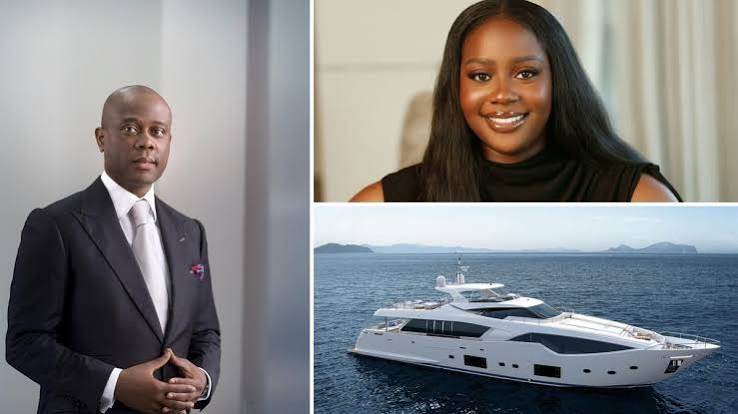
The daughter of late Nigerian banking executive, Herbert Wigwe has sold her father’s luxury yacht for $6.5 million which is the equivalent of N8.74 Billion following legal proceedings involving her, Otutochi Wigwe, and the company holding the vessel, Grosvenor Marine Ventures Limited.
This was contained in an online report obtained by The Tide Source in Port Harcourt recently.
The Source further clarified that $6. 5 Million dollars or N8.74 Billion was the asking price as at March this year but was unable to prove, if the said amount was exactly what the vessel went for.
The yacht, known as Chitochi, is a 2016 Custom Line 108 superyacht measuring approximately 33 metres (108 feet) in length. The transaction was handled by international yacht brokerage firm IYC, with its sales and charter consultant, Mark Elliott, overseeing the sale.
The disposal of the high-value vessel followed legal steps taken to address the corporate status of Grosvenor Marine Ventures Ltd., the company through which the yacht was held.
Otutochi Wigwe reportedly approached a court in the British Virgin Islands (BVI) to secure the restoration of the company to the corporate register, a move that enabled the necessary legal steps towards the sale of the vessel.
The proceedings were central to resolving the corporate issues affecting the company and facilitating the transaction, underscoring the legal complexities that may arise when valuable assets are held through corporate entities in foreign jurisdictions.
The sale is also significant in the context of estate administration, as luxury yachts require substantial financial commitments to maintain, even when they are no longer actively used by their owners or beneficiaries.
Such vessels typically attract considerable expenses, including crew salaries, insurance premiums, berthing charges, routine servicing and other maintenance costs, making their continued ownership a major financial responsibility.
Beyond the recurring expenses, luxury yachts are depreciating assets that may lose value over time. Their disposal can therefore form part of a strategy to preserve estate value, reduce liabilities and convert an expensive asset into liquid funds.
Wigwe, who was the former Group Chief Executive Officer of Access Holdings, died on February 9, 2024, in a helicopter crash in California, United States, alongside his wife, Chizoba; their son, Chizi; and former Nigerian Exchange Group chairman, Abimbola Ogunbanjo.
His death was widely mourned across Nigeria’s banking and business communities, where he was recognised for his contributions to the financial services industry, entrepreneurship and philanthropy.
Wigwe’s passing left behind an estate whose administration involves the management of assets and other financial interests, a process that can require legal and financial decisions to protect the interests of the estate and its beneficiaries.
The sale of Chitochi highlights the challenges associated with managing high-value assets held through corporate structures, particularly where the relevant companies and legal proceedings fall under different jurisdictions.
The $6.5 million transaction brings the yacht’s ownership chapter to a close while illustrating how legal procedures, financial considerations and estate management can intersect in the administration of the assets of a prominent business figure.
‘’We determined to get all our equipments and machinery functioning as we progress. For now we’ve about 105 workers, comprising daily paid harvesters and regular staffs. But aside these 105 staffs we also employ daily slashers who for now are about 100.
“During peak periods, hopefully on or before January 2026 we hope to increase our work force for maximum production”, the firm’s management Stated.
King Onunwor
Ariwera Ibibo-Howells, Yenagoa
Some traders at the Rumuwoji Market popularly known as Mile 1 Market have decried the continuous increase in the prices of food stuffs and other items in the ember season.
This was made known by the traders when The Tide visited the market recently.
The traders revealed varying changes in the prices of foodstuffs, with some commodities recording higher increase than others .
A trader Mrs Charity Obinna, at the market, said the price of yam remained the same last week and this week compared to the prices from last month to this month, adding that only a difference of about N100 to N200 was seen.
Another trader, Chukwuebuka Livinus who deals on garri, reported that the prices of some food commodities had been changing frequently.
According to him, the price of a bag of garri increased from N45,000 last week to N58,000 this week, representing an increase of N13,000.
Livinus described the increase as scary and called on the government to do something about it, especially as we get closer to the festive period.
A trader that deals on vegetables, Mrs Joy reported that a significant increase in the prices of pepper rose from N20,000 last week to N40,000 this week.
Similarly, the price of a bag of melon (egusi) increased from N420,000 toN490,000 this week.
In a separate report, Mrs Charity Obinna said that foodstuffs were generally cheaper last month than this month, with price differences ranging from N150 to N200 for some items.
Meanwhile, Giff Okoro reported a decrease in the price of tomatoes. According to her, a quantity of tomatoes that cost N45,000 last month now sells for N25,000, indicating a reduction of N20,000.
Another trader, Usman Ibrahim said the cost of transporting goods from the communities to urban areas where they are sold is one of the major reasons for high cost of goods.
He said transport cost has doubled due to the cost of petroleum products in Nigeria, adding the whole cost is part of the goods because “entrepreneurs must cover their cost and make their gains .
Ibrahim called on the government to help farmers and traders even with little capitals to expand and sustain their business.
Another trader, Mrs Choice Promise a fish retailer said a cartoon which sold at #35,000 last week now sells at #50,000 .
Promise complained that there is no gain or profit because the price has drastically increase and most people cannot afford to buy fish again.
“Mr. President’s Renewed Hope Agenda recognizes that economic ambition requires dependable infrastructure,” Tegbe said.
He added that investments in electricity infrastructure would strengthen the foundations for business expansion, employment and economic growth.
The Kankia substations comprise two 60 MVA, 132/33 kilovolt (kV) facilities designed to strengthen the transmission network serving Katsina State and neighbouring areas.
Tegbe said the infrastructure would improve the network’s ability to distribute available electricity, supporting commercial activities and household welfare.
He also urged residents to protect the facilities against vandalism and other activities that could disrupt electricity infrastructure, asking them to report suspicious activities to TCN or security agencies.
Katsina State Governor, Dikko Umaru Radda, described the project as a significant investment in the state’s electricity infrastructure.
Radda stated that improved electricity supply could support industrial development, economic growth and public service delivery.
He further commended the President, the Federal Ministry of Power and TCN for completing the project.
It would be noted that the latest projects come amid a broader government’s drive to address bottlenecks in Nigeria’s electricity transmission network, which has constrained the amount of electricity that can be delivered to distribution companies and end users.
Wali Chioma, Obasi Chidinma & Amarachi Uche
-
Opinion4 days ago
Ancestorial Worship: My Take (1)
-
 News14 hours ago
Fresh Ebola Scare As NCDC Records Two Cases
-
Niger Delta13 hours ago
PANDEF Seeks 50% Oil Derivation Allocation Increase
-
Rivers11 hours ago
Don Seeks Repositioning Of Tech Education For Dev
-
 Education12 hours ago
PAMO MEDICAL UNIVERSITY -Nullifies Arrest warrant on VC
-
 Education12 hours ago
IAUE MOVES TO END GHOST WORKERS SYNDROME AS 400 NEW NON-TEACHING STAFF UNDERGO MANDATORY ETHICS TRAINING
-
News14 hours ago
Customs Partners EFCC, NDLEA, Others To Tackle Money Laundering, Terrorism Financing
-
 News4 days ago
FG Must Address Nigerians’ Concerns On Reforms -Shettima …Warns Against Misuse of AI, Social Media